
UPI IDs

Yes, sharing a UPI ID is generally safe when someone needs it to send money.
A UPI ID is a payment address. It helps identify where money should be sent, but it is not a password and does not, by itself, authorise money to be taken from the account.
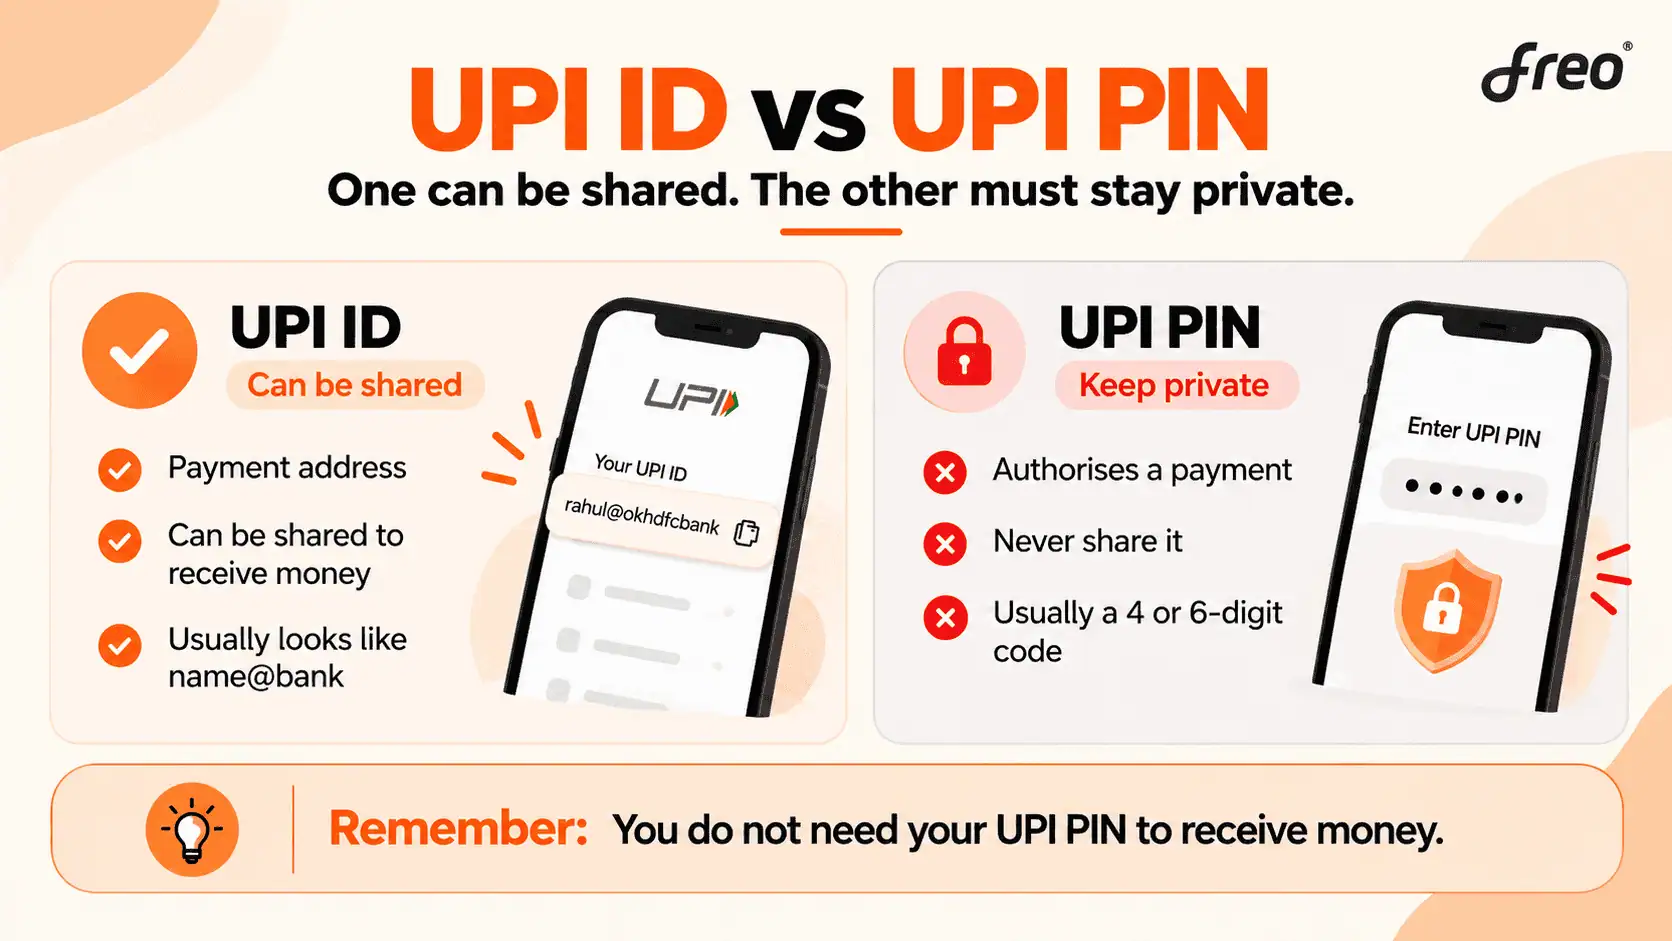
The important distinction is between a UPI ID and a UPI PIN. A UPI ID can be shared when receiving a payment. A UPI PIN is used to authorise a payment and should never be shared. NPCI specifically advises users not to share their UPI PIN and warns that entering a PIN after scanning a QR code is for making a payment, not receiving one.
Most UPI-related fraud therefore does not start with someone simply knowing a UPI ID. It starts when a person is persuaded to approve a payment, reveal an OTP or PIN, click a suspicious link, or give someone access to their device.
UPI ID vs UPI PIN: What's the Difference?
The easiest way to remember the difference is simple: the UPI ID helps someone pay you; the UPI PIN helps you authorise a payment.
UPI ID | UPI PIN |
|---|---|
Identifies the payment address | Authorises a UPI transaction |
Can be shared when receiving money | Must never be shared |
Usually looks like name@bank | Usually a 4- or 6-digit code |
Used to send or receive money | Used to approve a payment |
Note: If someone says a PIN, OTP or QR scan is required to receive a refund, cashback, prize or payment, stop and check what is actually happening. NPCI and RBI both warn users about scams built around this exact trick.
Freo's guide on how to find your UPI ID also explains the difference between a UPI ID and UPI PIN.
Can Someone Withdraw Money Using Your UPI ID?
Not simply by knowing your UPI ID.
A UPI ID is used to identify the account for a payment. Knowing it does not give another person your UPI PIN or automatically authorise a debit from the account.
The risk is that someone may use the UPI ID as part of a scam. For example, they might send a payment request and persuade the user to approve it, or send a QR code and claim that scanning it is necessary to receive money.
That is why the important question is not only “Who has my UPI ID?”, but also “What am I being asked to approve?”
Common UPI Scams to Watch Out For
Most UPI scams rely on social engineering rather than someone simply breaking into the UPI system. The scammer tries to make the user take an action that results in money being sent or sensitive information being disclosed.
Fake payment or collect requests
A person may claim to be sending a refund, making a payment or buying something and then send a payment request.
If the user approves the request and enters the UPI PIN, the money is debited from their account.
What to do: Check the amount and recipient before approving any request. If an unexpected request appears, decline it.
QR-code scams
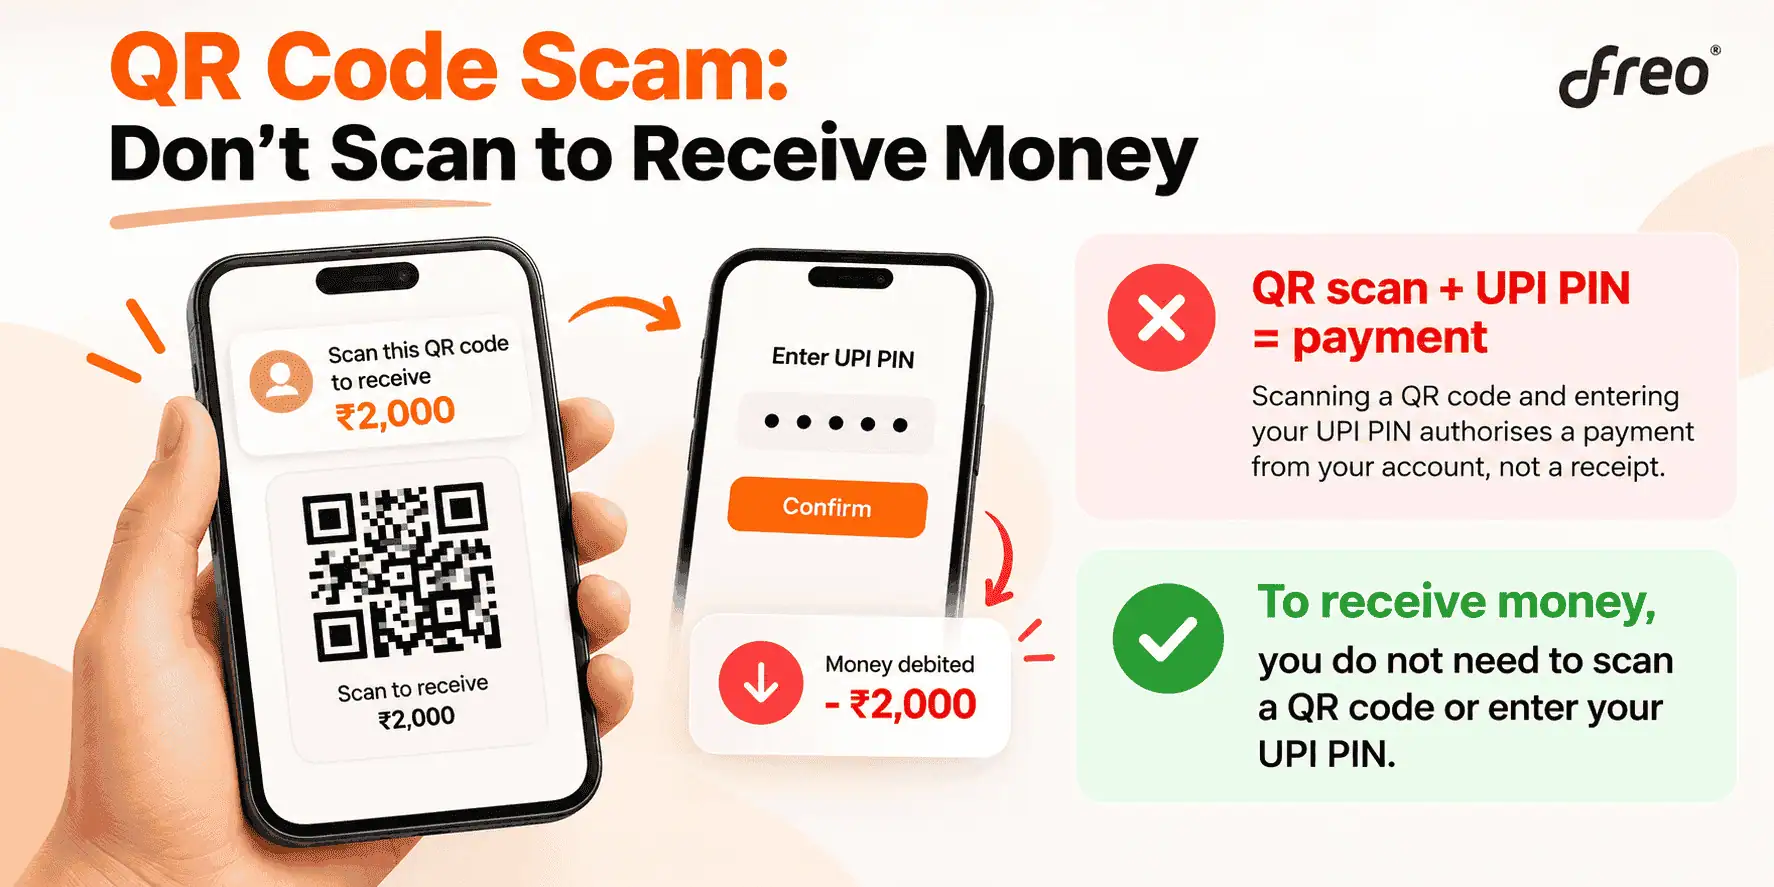
A scammer may send a QR code and say it is needed to receive cashback, a refund or a payment.
That is a red flag. Scanning a QR code and entering a UPI PIN is generally part of making a payment, not receiving one. NPCI and RBI both warn users not to scan unknown QR codes to receive money.
Fake customer support
Someone may pretend to be from a bank, UPI app or merchant and say that a payment has failed or an account needs to be verified. They may ask for an OTP, UPI PIN or access to the phone.
A genuine support representative should not need the user's UPI PIN.
Phishing links and fake refunds
Fraudsters may send links through SMS, email, WhatsApp or social media claiming to offer a refund, cashback or account update.
The link may lead to a fake website designed to collect banking information or install malicious software.
RBI has repeatedly advised users not to share sensitive payment information and to be cautious about suspicious links, calls and apps.
What Is Safe to Share and What Should Stay Private?
A simple rule can help avoid most confusion.
Generally safe to share when receiving money
UPI ID
Personal UPI QR code
UPI reference number when needed to track a particular transaction
Keep private
UPI PIN
OTP
Debit or credit card PIN
CVV
Passwords and banking login credentials
Screen access to the phone
Any authentication code received from the bank or payment service
Even when a piece of information is normally safe to share, context matters. For example, a transaction reference number can help a bank or merchant locate a payment, but a screenshot may contain additional information such as account details or balance.
What to Do If You Suspect UPI Fraud
If money has been debited without authorization or a suspicious transaction has already taken place, do not wait to see what happens.
Contact the bank or UPI app immediately
Use the bank's official customer-care channel or the payment app's support section to report the transaction.
Ask the bank what immediate steps are available to secure the account or UPI service.
Report financial cyber fraud on 1930
For online financial fraud in India, the National Cyber Crime Reporting Portal lists 1930 as the national helpline. It is available for immediate reporting of financial cyber fraud.
File the complaint online
A complaint can also be filed through the official National Cyber Crime Reporting Portal.
Keep useful details ready, including the transaction ID/UTR, transaction date, amount, bank or wallet details and any supporting screenshots or other evidence. The portal specifically asks for transaction details when reporting financial cyber fraud.
Report the transaction as soon as possible
RBI requires banks to provide channels for customers to report unauthorised electronic transactions and states that customers should notify their bank at the earliest.
There is an important distinction around customer liability. In certain third-party-breach situations where the customer is not at fault, reporting within three working days can result in zero liability under RBI's framework. If the loss resulted from the customer's negligence, such as sharing payment credentials, the customer can remain liable for the loss until the transaction is reported.
So, three days should not be treated as a waiting period. The safer approach is to report a suspicious transaction immediately.
Closing Thoughts
Sharing a UPI ID is a normal part of receiving digital payments. The ID works as a payment address, while the UPI PIN is what helps authorise a payment.
The simplest rule to remember is: share your UPI ID when needed, but never share your UPI PIN or OTP. If someone asks for a PIN, OTP or QR scan to send you money, stop and check the request before doing anything.
Pay with Confidence. Pay with Freo UPI.
Scan, pay and send money securely, anytime.

Frequently Asked Questions (FAQs)
Is it safe to share my UPI ID?
Yes. Sharing a UPI ID is generally safe when someone needs it to send money. The UPI ID itself does not authorise a debit from the account. The important thing is to never share the UPI PIN or OTP.
Can I share my UPI ID with anyone?
A UPI ID can be shared with someone who needs to pay you. However, if the person is unknown, it is still sensible to be cautious about unexpected payment requests, links or instructions that follow.
Is it safe to share a UPI ID to receive money?
Yes. A UPI ID is designed to identify the account to which money should be sent. Receiving money does not require entering the UPI PIN.
Is it safe to share a UPI transaction ID?
Generally, yes, when it is needed to identify or track a particular payment. A transaction reference can help a bank, merchant or payment app locate a transaction. NPCI's complaint system also uses transaction numbers or RRN details when handling transaction-related complaints.
However, a transaction ID is not the same as a UPI PIN. Never share OTPs, PINs or passwords along with it.
Is it safe to share the transaction ID from Google Pay?
Generally, the transaction ID can be shared when someone needs it to verify or trace a particular payment. If sharing a screenshot from Google Pay or another app, check whether it also reveals your balance, mobile number or other personal information.
If the issue concerns a failed or delayed payment, the transaction reference can be useful when contacting the bank or app support. Freo also has a guide on how a UPI reference number works and how to track a transaction
Can someone take money from my account if they know my UPI ID?
Not simply because they know the UPI ID. The greater risk is being tricked into approving a payment or sharing authentication details. An unexpected payment request should be declined rather than approved.
Do I need my UPI PIN to receive money?
No. A UPI PIN is used to authorise a payment from the account. NPCI specifically warns users that entering a UPI PIN after scanning a QR code is for making a payment, not receiving one.
Is it safe to share my UPI ID on social media?
It is generally possible to receive money through a publicly shared UPI ID, but there is a privacy trade-off. Depending on how the UPI ID is formatted, it may reveal a name or mobile number. Publicly posting it can also attract unwanted payment requests or scam attempts.
For a private transaction, sharing the UPI ID directly with the person paying is usually preferable.
Is it safe to share my UPI QR code?
A personal UPI QR code can be shared when someone needs to pay you. However, never scan an unknown QR code or enter your UPI PIN because someone says it is necessary to receive money. RBI specifically warns users about QR-code scams.
Is UPI safe?
UPI has authentication and security controls, but no digital payment system is completely free from fraud. Many UPI scams rely on convincing users to approve a payment, share sensitive credentials, click a malicious link or install an unsafe app. NPCI and RBI both publish fraud-awareness guidance around these risks.
What should I do if I accidentally shared my UPI PIN or OTP?
Contact the bank immediately through its official support channel and report the issue. If an unauthorised transaction has already occurred, report the financial cyber fraud through 1930 and the National Cyber Crime Reporting Portal as soon as possible.
What happens if someone knows my UPI ID?
Usually, nothing happens simply because someone knows the ID. They may be able to send money or payment requests depending on the UPI setup, but knowing the UPI ID alone does not give them the UPI PIN. The user should still be careful about unexpected requests and messages.
Naina Rajgopalan
Naina Rajgopalan has a thing for numbers and a deep fascination to learn about all things finance. She's been money-wise from a young age and has always shared her knowledge and tips with those around her. Being a part of the content team at Freo, a neobank that offers flexible and customised financial products, along with benefits such as insurance on balance, safe & secure banking, and so on, Naina stays updated with the latest of what happens in the banking and fintech industries. She has taken upon herself to share her knowledge with readers across all walks of life to help them manage their finances and budgets better, so they can make better decisions while spending, borrowing, investing and saving.